Florida’s 2026 Property Tax Amendment 3
What Florida Businesses Need to Know About Amendment 3
Florida voters approved Amendment 3 in the November 3, 2026 General Election. The amendment makes significant changes to Florida's property tax system beginning January 1, 2027.
Understand Amendment 3 Implementation TimelineFlorida's 2026 Property Tax Amendment
Amendment 3 changes homestead exemptions, non-homestead property assessments, residency requirements and the use of county and municipal ad valorem tax revenue. These changes will affect Florida businesses, renters, homeowners and local communities.
The Florida Chamber is committed to helping Florida's business community understand how Amendment 3 will be implemented. This page will track implementing legislation and other statewide developments as the amendment takes effect.
Understanding Amendment 3
Approved by approximately 62 percent of Florida voters, Amendment 3 increases the homestead exemption for qualifying residents and reduces the annual assessment increase cap for non-homestead properties from 10 percent to 5 percent. It also sets new residency requirements for the increased exemption and limits county and municipal ad valorem revenue to specified core services.
The amendment takes effect January 1, 2027, and several provisions depend on future action by the Legislature.
Get the Facts on Amendment 3
Start with these Florida Chamber resources to understand what Amendment 3 changes and how Florida's property tax system works.
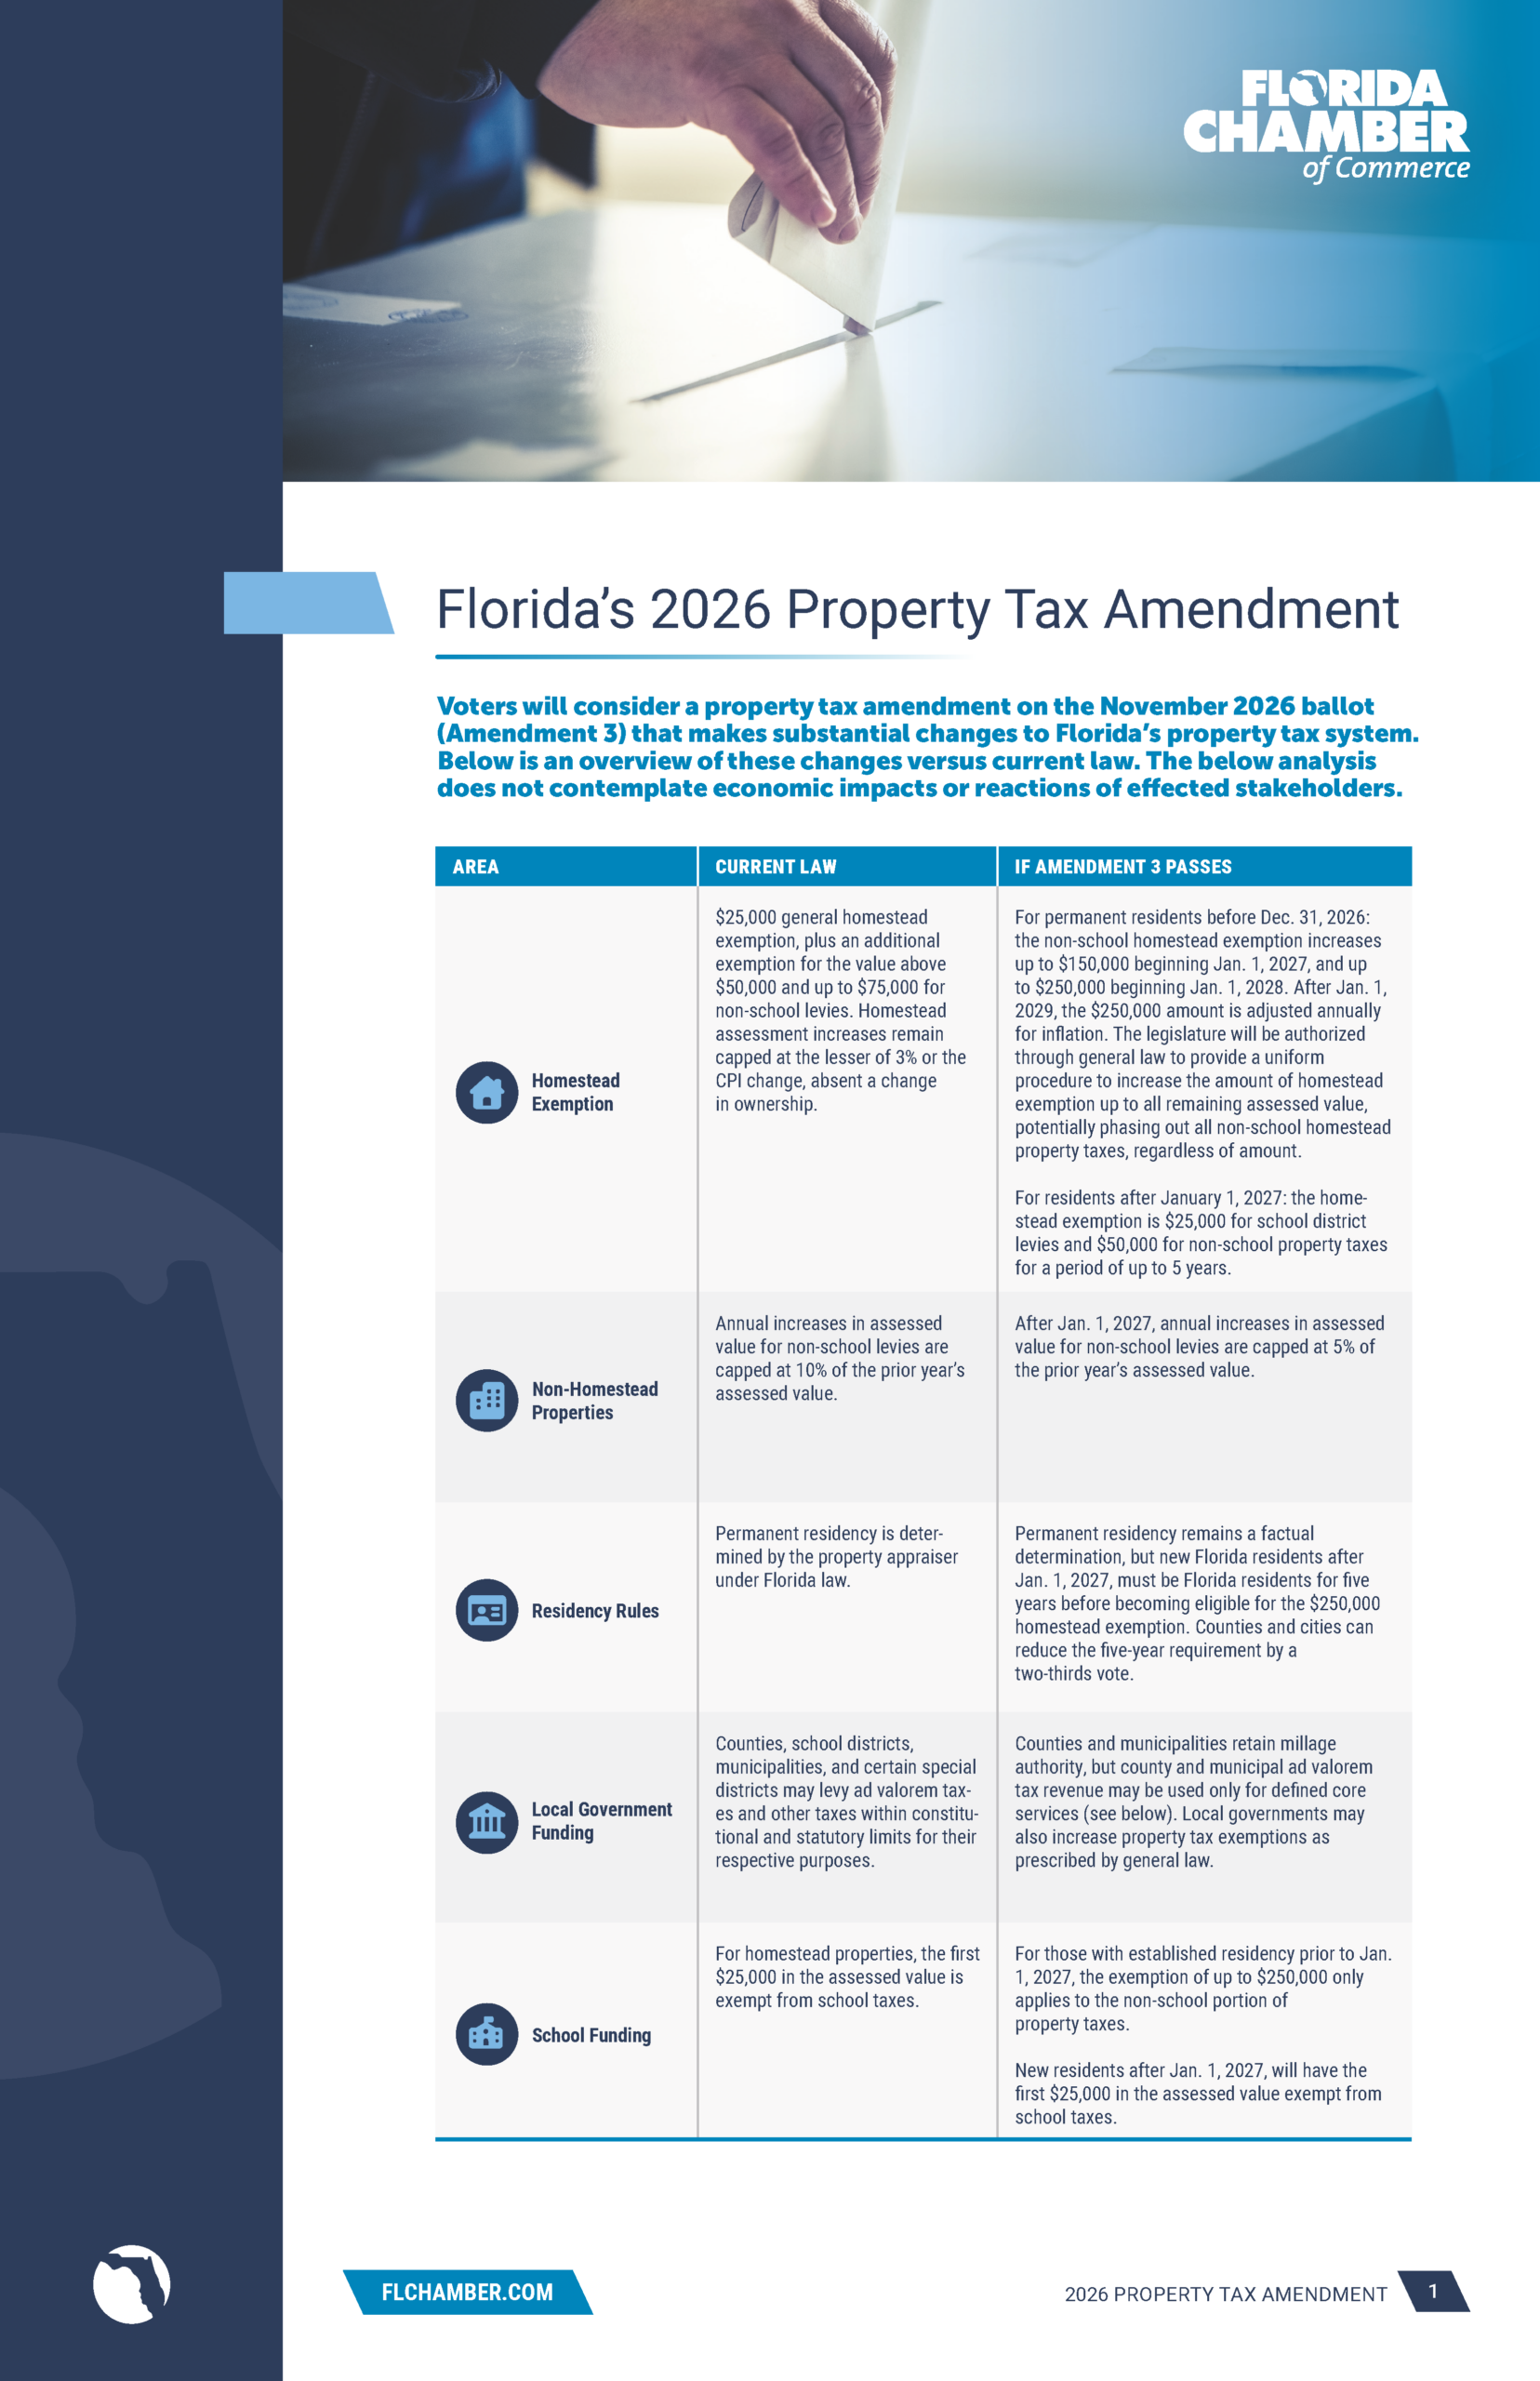
Current Law vs. Amendment 3
See a side-by-side comparison of Florida's property tax system before and after Amendment 3.
View the Comparison
Understand How Florida's Property Tax System Works
Learn about Florida's property tax system, including homestead and non-homestead classifications and property tax collections. Note: the primer reflects pre-amendment law. An updated 2026 primer is coming soon.
Read the PrimerWhat Amendment 3 Changes
Homestead Exemption
Beginning with the 2027 tax roll, the homestead exemption for non-school taxes increases to $150,000. It rises to $250,000 in 2028 and is adjusted for inflation after that. A $25,000 exemption continues to apply to school taxes.
Non-Homestead Property
Beginning in 2027, annual assessment increases for non-homestead property are capped at 5 percent for non-school levies, down from 10 percent. This includes commercial, industrial and rental property.
Residency Requirements
New Florida residents after January 1, 2027, must be Florida residents for five years before becoming eligible for the $250,000 homestead exemption. Counties and municipalities can reduce the five-year requirement by a two-thirds vote.
Local Property Tax Revenue
County and municipal property tax revenue may be used only for public safety, education, infrastructure, natural resources, bond debt service, employee retirement benefits, and operations and administration.
Who Is Affected by Amendment 3?
Amendment 3 includes changes affecting both homestead and non-homestead property and will have broader implications for local property tax collections. Understanding which provisions apply to different types of property can help Floridians evaluate how the amendment will affect them and their communities.
Florida Homeowners
Qualifying homestead property owners will be directly affected by the increase in the homestead exemption for non-school property taxes. The amendment also establishes different timing for the increased exemption for certain new Florida residents.
Businesses & Commercial Property
Commercial property is generally classified as non-homestead property. Amendment 3 will reduce the annual cap on assessment increases for non-homestead property from 10 percent to 5 percent.
Renters & Rental Property
Rental and investment properties generally do not qualify for the increased homestead exemption. Non-homestead residential property will be subject to the 5 percent annual assessment increase cap.
Local Communities & Governments
The amendment will affect local property tax collections and includes provisions governing the use of county and municipal property tax revenue. Estimated fiscal impacts vary by county.
Implementation Timeline
-
November 2026 – 2027 Legislative Session
Implementing legislation expected.
-
Jan. 1, 2027
Homestead exemption increases up to $150,000 for qualifying residents; non-homestead assessment cap changes to 5%.
-
Jan. 1, 2028
Homestead exemption increases up to $250,000 for qualifying residents.
-
After Jan. 1, 2029
The $250,000 exemption is adjusted annually for inflation, with a process for future increases by general law. The Legislature must also prescribe a schedule to eliminate remaining non-school homestead property taxes.
-
After Jan. 1, 2032
New residents after Jan. 1, 2027, begin qualifying for the increased $250,000 non-school homestead exemption.
Explore Amendment 3 by County
Estimated revenue impacts vary across Florida's 67 counties. Select a county below to explore its estimated fiscal impact and county government operating millage rate assuming property values remain flat and the millage rate remains unchanged.
Figures are shown in millions. Parentheses indicate estimated reductions in revenue. County-level estimates and operating millage rates are presented for educational purposes.
Data sources: Florida Office of Economic and Demographic Research, Revenue Estimating Conference adopted impact by county for CS/HJR 1F (July 10, 2026), and Florida Department of Revenue.
Amendment 3 Updates
Florida Voters Approve Amendment 3
Florida voters approved Amendment 3 in the November 3 General Election with approximately 62 percent of the vote, according to unofficial results. That exceeds the 60 percent required to amend the Florida Constitution. The amendment takes effect January 1, 2027.
The Florida Chamber will be actively engaged in the implementation of Amendment 3 to help avoid negative impacts on Florida businesses, renters and job creators.
Official Ballot Language
The ballot title and summary below are the official language for Amendment 3 as it appeared on the November 3, 2026 General Election ballot.
This amendment increases the homestead exemption, for all non-school taxes, to $150,000 in 2027 and $250,000 in 2028, and adjusts for inflation thereafter. It requires the Legislature to prescribe a uniform procedure for counties and municipalities, for their respective levies, to increase the homestead exemption up to full assessed value, and allows special districts, subject to referendum approval, to do the same.
Persons who are not Florida residents on December 31, 2026, will receive the existing homestead exemption upon qualifying for a homestead exemption, with the increased homestead exemption beginning with the fifth year of exemption, to the extent permitted by the U.S. Constitution.
This amendment reduces the annual cap on assessment increases for non-homestead properties from 10% to 5%.
This amendment requires counties and municipalities to use property taxes solely for public safety, education and schools, infrastructure, natural resources, bond debt service, retirement benefits for employees, and operations and administration. Other expenditures may be approved by county officers or county or municipal governing bodies unless prohibited by general law, notwithstanding Article VII, Section 9(a) of the Florida Constitution, which allows counties and municipalities to levy property taxes for their respective purposes.
This amendment takes effect January 1, 2027.
Amendment 3 FAQs
What is Amendment 3?
Amendment 3 is an amendment to the Florida Constitution addressing homestead exemptions, non-homestead property assessments, residency requirements and provisions governing county and municipal property tax revenue.
Did Amendment 3 pass?
Yes. It received approximately 62 percent of the vote in the November 3, 2026 General Election, exceeding the 60 percent threshold.
How much voter approval did Amendment 3 need?
At least 60 percent of voters voting on the measure must approve a proposed amendment for it to become part of the Florida Constitution.
When does Amendment 3 take effect?
The amendment takes effect January 1, 2027.
When will I see a change on my tax bill?
The amendment applies beginning with the 2027 tax roll. The Florida Chamber will provide more detail on timing as implementing legislation is adopted.
What happens next?
The Legislature is expected to pass a bill implementing the amendment, likely before or during the 2027 Legislative Session. It is also required to prescribe a uniform procedure for counties and municipalities to further increase the homestead exemption. Local governments will adopt budgets and millage rates for the 2027 tax year under the new rules.
How does the homestead exemption change?
The amendment increases the homestead exemption for non-school taxes to $150,000 in 2027 and $250,000 in 2028, with inflation adjustments thereafter.
Does the amendment affect school taxes?
No. The increased exemption applies to non-school taxes. A $25,000 homestead exemption continues to apply to school taxes.
How does Amendment 3 affect commercial property?
Commercial property does not qualify for the homestead exemption. Only the portion of a property that an owner uses as their permanent residence can qualify. Beginning in 2027, the annual cap on assessment increases for non-homestead property, including commercial property, is reduced from 10 percent to 5 percent for non-school levies.
How does Amendment 3 affect rental property?
Non-homestead rental property is subject to the reduction in the annual assessment increase cap from 10 percent to 5 percent.
How are new Florida residents addressed?
New Florida residents after January 1, 2027, must be Florida residents for five years before becoming eligible for the $250,000 homestead exemption. Counties and municipalities can reduce the five-year requirement by a two-thirds vote. Property appraisers will make residency determinations, and implementing legislation is expected to provide more detail.
Can local governments still raise millage rates?
Yes. Counties and municipalities keep their millage authority within existing constitutional limits. However, county and municipal ad valorem revenue may only be used for the specified core services.
What is a millage rate?
A millage rate is the rate used to calculate property taxes. One mill represents $1 in tax for every $1,000 of taxable property value.
Amendment 3 & Property Tax Resources
Current Law vs. Amendment 3
Compare Florida's property tax system before and after Amendment 3.
View Comparison →Florida Property Tax Primer
Learn how Florida's property tax structure works. Note: the primer reflects pre-amendment law. An updated 2026 primer is coming soon.
Read Primer →EDR Revenue Estimating Conference Results
Review the adopted statewide and county-level revenue impact estimates for CS/HJR 1F (July 10, 2026).
View EDR Results →Florida Chamber Property Tax Letter
Review the Florida Chamber's letter addressing Florida property tax policy.
Read Letter →Official Amendment 3 Information
Read the official amendment language from the Florida Department of State.
View Official Information →Jax Tax Facts
Explore additional educational information focused on Amendment 3 and Jacksonville.
Visit Resource →Impacts to Homeowners
Real Estate News: Florida Homestead Tax Vote Could Affect 60% of Homeowners
Explore Perspective →Tax Foundation Analysis of Amendment 3
Amendment 3: A Restructuring of Florida's Local Tax Base
Explore Perspective →Stay Informed
The Florida Chamber will continue to provide updates, data and educational resources as Amendment 3 is implemented.
For questions about Amendment 3 or Florida's property tax system, contact Carolyn Johnson, Vice President of Government Affairs, at 850-521-1235 or cjohnson@flchamber.com.
Contact Carolyn